Home Insurance
PROTECT YOUR HOME.
PROTECT YOUR FUTURE.
Your home is more than just a house; it’s where life happens. Tuve Insurance helps protect what matters most with comprehensive homeowners insurance coverage you can count on.
- Dwelling Coverage
- Liability Protection
- Medical Payments
- Personal Property
- Loss of Use
- Other Structures
GET A QUICK QUOTE
it only takes a minute
Your information is secure and will never be shared
Home Insurance in Lakeville, MN
Your home is more than a building. It is where your family gathers. The right home insurance protects that investment when fire, wind, hail, theft, water damage, or another covered loss disrupts your life. Tuve Insurance helps homeowners in Lakeville and throughout Minnesota compare coverage options.
Whether you are buying your first house, reviewing an older policy, or searching for better Minnesota home insurance rates, our independent agency can help. We make homeowners insurance simple to understand.
What Does Home Insurance Cover?
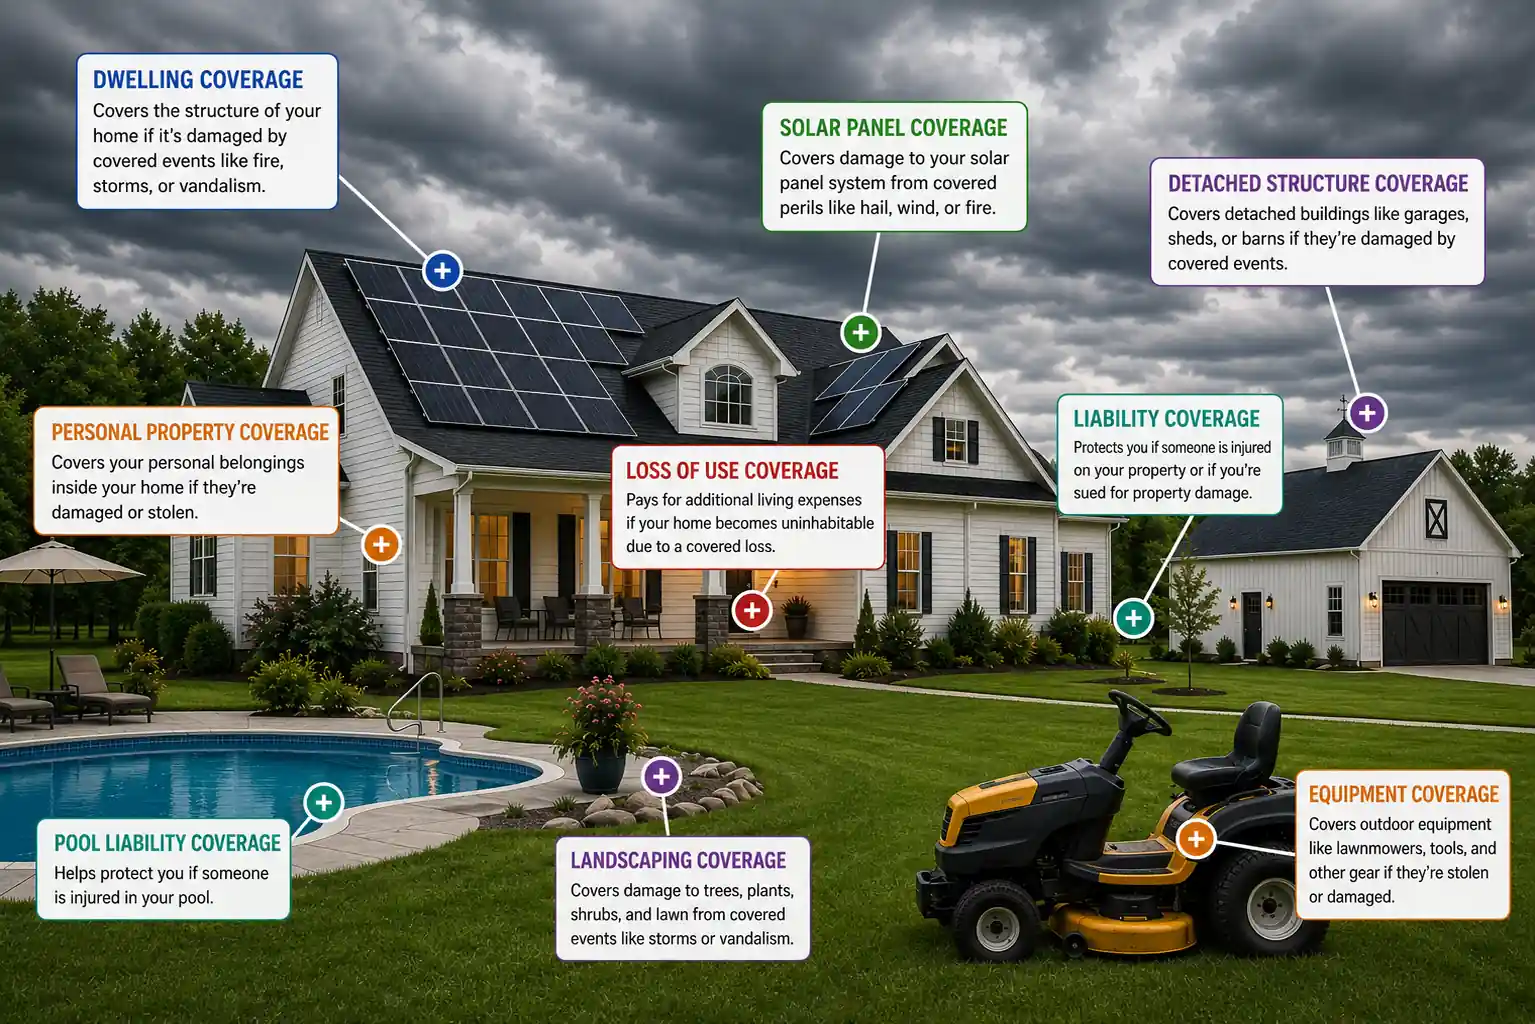
A standard home insurance policy combines several protections. Dwelling coverage helps pay to repair or rebuild the structure of your home after a covered loss. Other structures coverage may protect detached garages, sheds, and fences. Personal property coverage helps replace belongings when they are damaged or stolen.
Personal liability coverage can help protect you when someone claims you caused bodily injury or property damage. Medical payments coverage may pay medical expenses when a guest is injured on your property. Loss of use coverage may help pay for temporary housing and meals if a covered claim makes your home unlivable.
Every policy contains limits, exclusions, deductibles, and conditions, so review the details with a Minnesota insurance agent.
Coverage Designed for Minnesota Homes
Minnesota homeowners face severe thunderstorms, wind, hail, heavy snow, freezing temperatures, ice dams, and burst pipes. A strong Minnesota home insurance policy should be reviewed with these risks in mind.
Wind and hail deductibles deserve special attention. Some policies use a flat deductible; others apply a percentage deductible based on the home’s insured value. For example, a two percent wind and hail deductible on a home insured for $400,000 equals $8,000. Knowing that amount before a storm can prevent an unpleasant surprise.
Water backup and sewer backup coverage may also be important. Standard home insurance does not cover every type of water loss. Optional endorsements may protect against damage caused by a backed-up sump pump, drain, or sewer line. Service line coverage, equipment breakdown coverage, and increased replacement cost coverage are other options worth discussing.
Replacement Cost Matters
The dwelling limit should reflect the estimated cost to rebuild your home, not its market, tax, or purchase value. Construction labor, materials, debris removal, building codes, and local demand can all affect replacement cost.
Extended replacement cost coverage may provide an additional amount above the dwelling limit when rebuilding costs rise after a widespread disaster. Ordinance or law coverage can help pay for required upgrades when damaged portions of an older home must meet current codes.
Personal property can usually be insured on an actual cash value or replacement cost basis. Actual cash value subtracts depreciation. Replacement cost coverage generally pays based on the cost of buying a comparable new item. Jewelry, collectibles, fine art, and certain electronics may have special limits and may need separate scheduling.
How Much Does Home Insurance Cost in Minnesota?
The cost of home insurance in Minnesota depends on the home’s location, age, construction type, roof condition, replacement cost, prior claims, deductible, coverage limits, and endorsements. Insurance companies may also consider protective devices and whether you bundle home and auto insurance.
The lowest premium is not always the best value. A cheaper policy may have a higher wind and hail deductible, lower water backup limits, actual cash value roof settlement, or fewer replacement cost protections. Tuve Insurance compares more than price and helps you consider how the policy may respond when you need it.
Why Work With Tuve Insurance?
Tuve Insurance is a veteran-owned and operated independent insurance agency located in Lakeville, Minnesota. We are not limited to one insurance company, allowing us to compare homeowners insurance quotes, coverage options, deductibles, and discounts from multiple carriers.
Our goal is to provide local service, practical guidance, and insurance solutions that fit your property and budget. We can also help you explore multi-policy discounts by combining home insurance with auto, umbrella, motorcycle, boat, life, or business insurance. As your needs change, we can review your protection after renovations, additions, or valuable purchases.
Get a Minnesota Homeowners Insurance Quote
Do not wait until after a storm, fire, theft, or water loss to discover a gap in your coverage. Contact Tuve Insurance for a homeowners insurance review or a home insurance quote in Lakeville, MN. Call 952-469-0428 to compare options, ask questions, and protect the home you worked hard to build.
Frequently Asked Questions
Minnesota law does not generally require homeowners insurance, but mortgage lenders usually require borrowers to maintain coverage. Even without a mortgage, insurance can protect your home, belongings, and finances from major losses.
Standard homeowners insurance does not cover flooding caused by rising surface water. Separate flood insurance may be available through the National Flood Insurance Program or private flood insurers. Water backup coverage is different and may be added by endorsement.
Many policies cover sudden hail damage, subject to the deductible, exclusions, roof settlement terms, and condition of the roof. Some policies pay replacement cost, while others may apply depreciation or actual cash value to older roofs.
You may reduce your premium by bundling home and auto insurance, selecting a higher deductible, improving roof condition, installing protective devices, maintaining a claim-free history, and comparing quotes from multiple insurance companies through an independent agent.