Motorcycle Insurance
RIDE WITH FREEDOM.
PROTECT WHAT MATTERS.
Motorcycle insurance helps protect you, your bike, and your financial future. Tuve Insurance offers coverage options designed for riders in Minnesota and Iowa. Keep your knees in the breeze and reach out to us today.
- Liability Coverage
- Comprehensive
- Colision
- UM & UIM
- Medical Payments
- Custom Options
GET A QUICK QUOTE
it only takes a minute
Your information is secure and will never be shared
Protect Your Bike, Your Passengers, and Your Financial Future
Minnesota offers riding from lake country routes to daily Twin Cities commutes. However, motorcycles create risks that auto insurance does not fully address. A crash, theft, hailstorm, fire, or liability claim can cause repairs, medical bills, lost income, and legal costs. Motorcycle insurance helps protect your bike and finances.
Tuve Insurance provides motorcycle insurance in Lakeville, MN, for riders throughout Minnesota. As a veteran-owned independent agency, we compare quotes from multiple carriers instead of offering just one.
Whether you ride a cruiser, touring bike, sport bike, trike, scooter, vintage motorcycle, or custom bike, call 952-469-0428 for personalized help.
What Does Motorcycle Insurance Cover?
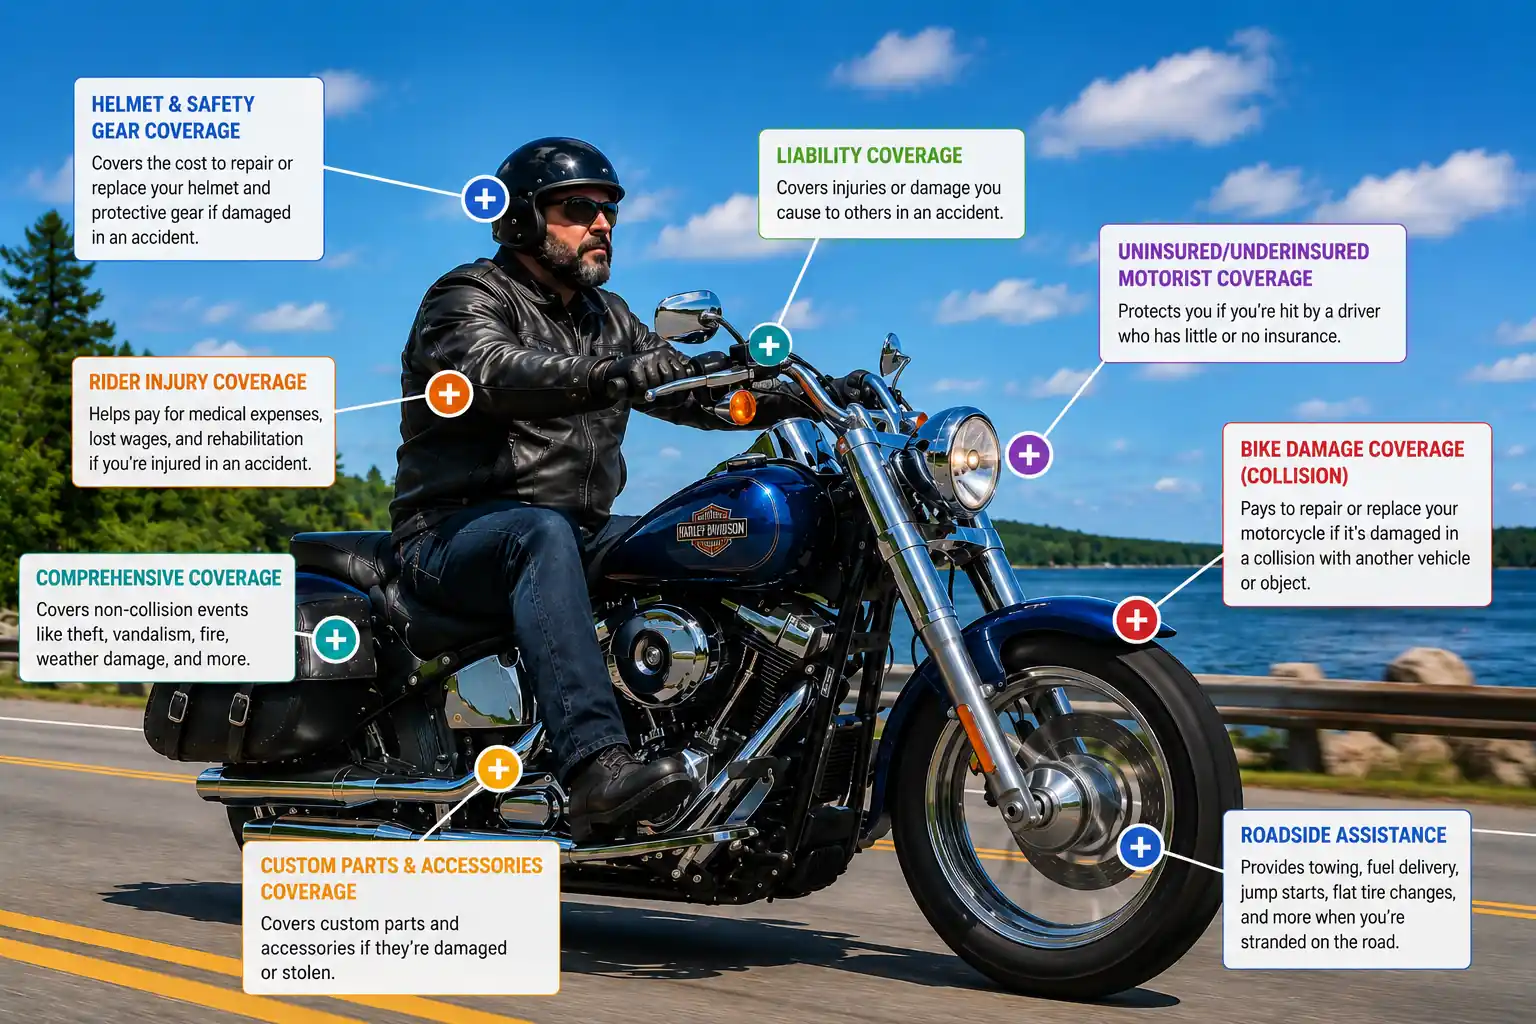
A motorcycle insurance policy can combine several protections. Liability insurance helps pay covered bodily injury and property damage claims when you are responsible for an accident. It may also cover defense expenses, settlements, or judgments, subject to policy limits and conditions.
Collision coverage helps repair or replace your motorcycle after a covered crash. Comprehensive insurance generally covers non-collision losses like theft, vandalism, fire, hail, wind, falling objects, and animal strikes. Both coverages usually include deductibles.
Uninsured and underinsured motorist coverage may help when an at-fault driver has no insurance or insufficient limits. Optional medical coverage may also be available. Because motorcycle injuries can be serious, riders should review these protections rather than choose a policy based only on price.
Minnesota Motorcycle Insurance Requirements
Minnesota motorcycle owners must maintain liability security for registered motorcycles. Unlike a standard Minnesota auto policy, a basic motorcycle policy is not required to include Personal Injury Protection, or PIP. PIP from your personal auto insurance generally does not cover injuries suffered while riding your motorcycle. Optional first-party medical protection may be available, so review the policy before riding.
Minnesota also requires a valid motorcycle endorsement or instruction permit to operate on public roads. Proof of current motorcycle insurance may be required during testing, registration, or law-enforcement interactions.
Buying only minimum motorcycle liability insurance may leave you exposed after a serious accident. Higher liability limits and a personal umbrella policy can better protect your savings, income, home equity, and future earnings.
Coverage for Custom Parts, Accessories, and Riding Gear
Many riders invest in saddlebags, custom paint, chrome, exhaust systems, electronics, upgraded wheels, safety equipment, and performance parts. A basic policy may offer limited coverage for these additions.
Custom parts and equipment coverage can protect eligible upgrades. Keep receipts, photographs, appraisals, and a current modification list. Ask if your helmet, jacket, boots, gloves, communications equipment, and other riding gear are covered and what limits apply.
Roadside assistance may help with towing, batteries, flat tires, fuel delivery, or breakdowns. Trip interruption may cover lodging, meals, or transportation when a covered problem leaves you stranded. Total-loss replacement or agreed-value coverage may also be available.
Motorcycle Insurance for Different Types of Bikes
Tuve Insurance can help riders compare coverage for Harley-Davidson, Honda, Indian, Yamaha, Kawasaki, Suzuki, BMW, Ducati, Triumph, KTM, and other brands. We can also explore insurance for touring bikes, sport motorcycles, cruisers, scooters, mopeds, trikes, classic motorcycles, and custom-built bikes.
A financed motorcycle may require collision and comprehensive coverage. A collector bike may need agreed-value protection. A high-performance sport bike may be priced differently than a small commuter motorcycle. Accurate information about the bike, drivers, storage, mileage, modifications, and use helps produce a reliable insurance quote.
How Much Does Motorcycle Insurance Cost in Minnesota?
Motorcycle insurance rates in Minnesota depend on the rider’s age, experience, driving record, claims history, ZIP code, motorcycle type, engine size, value, annual mileage, storage, selected limits, and deductibles. Insurers may also consider if the bike is financed, customized, used for commuting, or operated by multiple riders.
Discounts may be available for completing a motorcycle safety course, insuring multiple bikes, maintaining a clean record, bundling policies, installing anti-theft devices, or paying in full.
Searching for cheap motorcycle insurance in Minnesota can be a useful starting point. However, the lowest premium may come with low limits, high deductibles, restrictive exclusions, or insufficient protection for accessories. Affordable motorcycle insurance should balance cost with dependable coverage.
Should You Cancel Motorcycle Insurance During Winter?
Minnesota has a shorter riding season, but canceling your policy during winter can cause problems. Your motorcycle can still be stolen, vandalized, damaged by fire, or affected by a building collapse while stored. A coverage lapse may also affect future pricing or violate a lender’s requirements.
Some carriers price annual motorcycle policies with seasonal use already considered. Others may offer a lay-up option that reduces certain coverage while keeping comprehensive protection. Before changing or canceling coverage, ask Tuve Insurance how the decision effects theft protection, physical damage, registration, financing, and future premiums.
Why Choose Tuve Insurance?
Tuve Insurance is a veteran-owned independent insurance agency located in Lakeville, Minnesota. We take time to understand what you ride, how often you ride, where the motorcycle is stored, who operates it, and what protection matters most.
Because we represent multiple insurance companies, we can compare Minnesota motorcycle insurance quotes, coverage limits, deductibles, discounts, and optional endorsements. We can also coordinate your motorcycle policy with auto, homeowners, renters, boat, umbrella, life, and business insurance.
Request a Motorcycle Insurance Quote Today
Before your next ride, make sure your coverage matches your motorcycle, lifestyle, and financial goals. Contact Tuve Insurance for a motorcycle insurance review in Lakeville, MN.
Call 952-469-0428 to compare motorcycle insurance quotes, explore available discounts, and choose protection for your bike, passengers, accessories, and future.
Frequently Asked Questions
Yes. Owners must maintain liability coverage for registered motorcycles operated in Minnesota. The required coverage is not the same as a standard personal auto policy, so riders should review their motorcycle policy separately.
Not automatically. A basic motorcycle policy is not required to include PIP, and PIP from a personal auto policy generally does not cover injuries sustained while riding your motorcycle. Ask about optional first-party medical coverage.
Comprehensive coverage generally protects against motorcycle theft, subject to the deductible, exclusions, storage requirements, and policy terms. Liability-only insurance does not pay to replace your stolen motorcycle.
Some policies cover permissive operators, but restrictions may apply based on age, licensing, experience, household status, or specifically excluded drivers. Regular operators should be disclosed to your insurance agent.