General Liability Insurance
PROTECT YOUR BUSINESS.
BE COVERED. BE CONFIDENT.
Accidents happen. Tuve Insurance helps Minnesota and Iowa businesses protect against common liability risks with customized General Liability Insurance built for your business. Request a quote today.
- Bodily Injury
- Products & Completed Operations
- Legal Defense Costs
- Property Damage Coverage
- Personal & Advertising Injury
- Medical Payments
GET A QUICK QUOTE
it only takes a minute
Your information is secure and will never be shared
Protect Your Minnesota Business from Everyday Liability Risks
Operating a business brings both opportunities and liability risks. Incidents such as customer injuries, employee-caused property damage, or claims of harmful advertising can occur. Commercial general liability insurance helps protect your company from lawsuits and related expenses after a covered event.
Tuve Insurance offers general liability insurance in Lakeville, MN, for Minnesota businesses. As a veteran-owned independent agency, we help business owners compare liability insurance quotes from multiple carriers. Call Tuve Insurance at 952-469-0428 to discuss coverage tailored to your operations.
What Is General Liability Insurance?
General liability insurance, also known as commercial general liability or CGL insurance, is essential for businesses. It typically covers claims involving third-party bodily injury, property damage, and personal or advertising injury.
The Minnesota Department of Commerce lists bodily injury, property damage, personal injury, and false or misleading advertising as major liability categories covered by a CGL policy.
A general liability policy does not cover all business risks. It does not replace commercial property, workers’ compensation, professional liability, cyber liability, commercial auto, or employment practices liability insurance. These exposures require separate policies.
What Does Business Liability Insurance Cover?
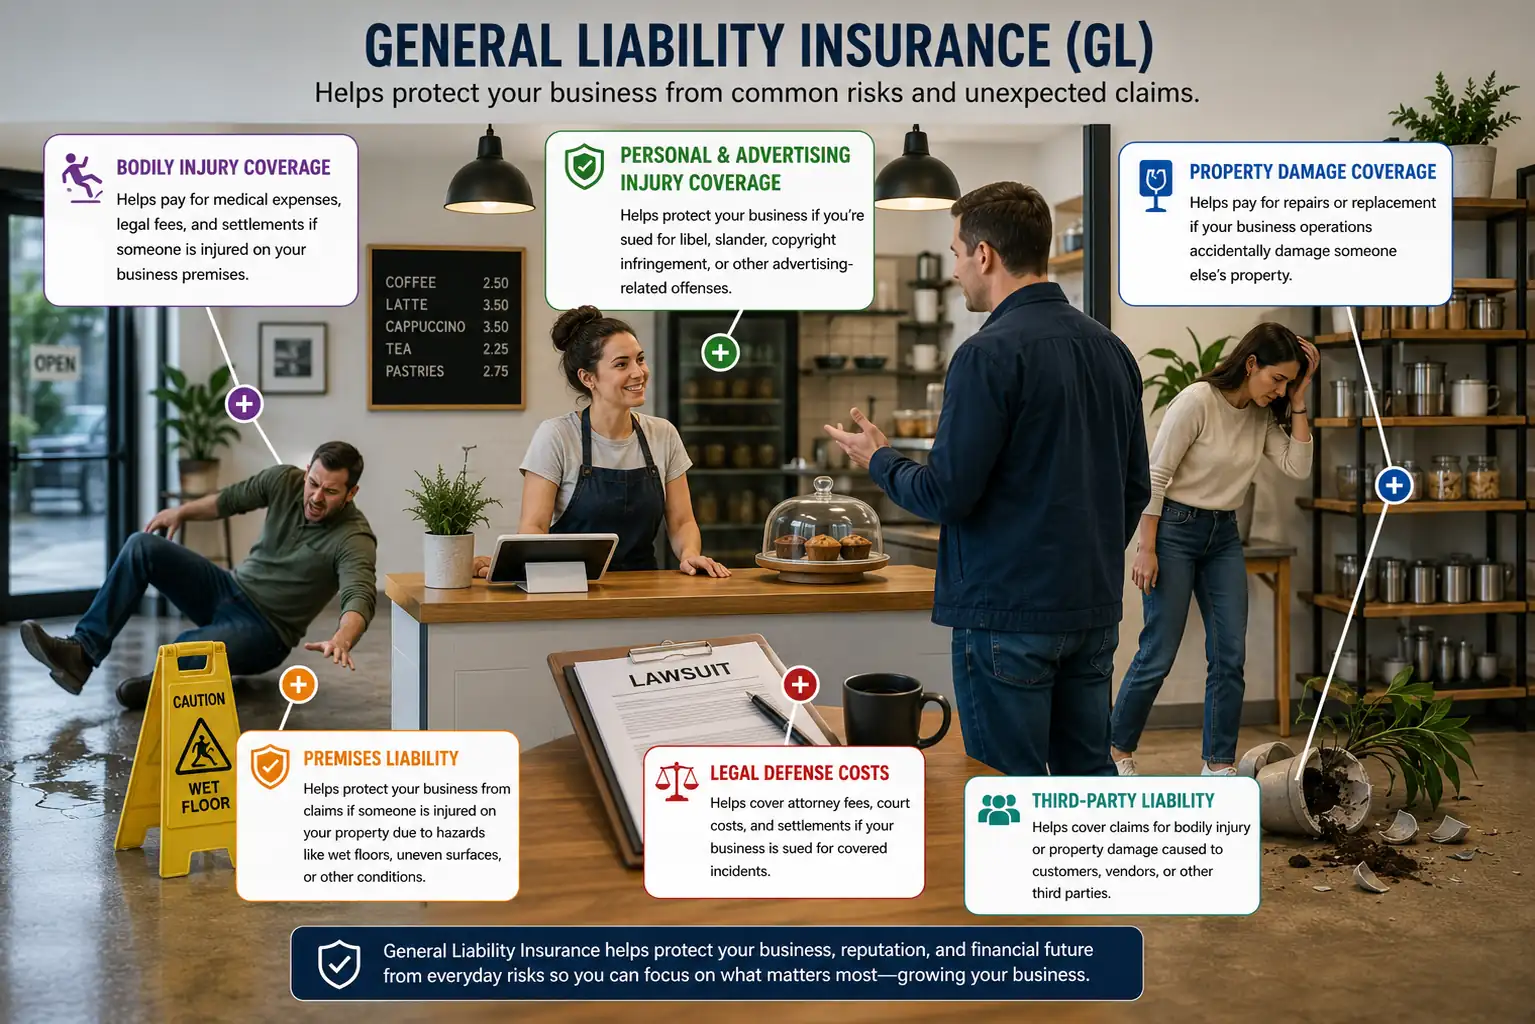
Bodily injury coverage applies when a customer, visitor, vendor, or other third party is injured due to your business operations. For example, if a customer slips on the floor, coverage may help pay medical expenses, defense costs, settlements, or judgments, subject to policy terms.
Property damage liability helps if your business causes physical damage to someone else’s property. For instance, a contractor might damage flooring, or an employee could break equipment at a client’s site.
Personal and advertising injury coverage addresses claims such as libel, slander, wrongful eviction, invasion of privacy, or advertising offenses. Intentional acts and knowingly false statements are typically excluded.
Medical payments coverage may pay limited expenses for an injured third party without requiring a lawsuit. Products-completed operations coverage applies if completed work or products cause covered bodily injury or property damage.
General Liability Insurance for Minnesota Contractors
Contractors face unique risks due to changing job sites, subcontractor involvement, and potential impact on others’ property. General liability insurance helps protect electricians, plumbers, roofers, landscapers, painters, remodelers, HVAC companies, carpenters, concrete contractors, and other trades.
Some Minnesota contractor licenses require proof of commercial general liability insurance. The Minnesota Department of Labor and Industry accepts an ACORD 25 certificate or similar evidence of coverage for certain licensing requirements.
Your policy should accurately reflect your work, payroll, sales, subcontractor costs, and territory. Contractors should also obtain certificates of insurance from subcontractors and confirm required additional insured language when needed.
Certificates of Insurance and Additional Insureds
Customers, landlords, municipalities, lenders, and general contractors may request a certificate of insurance before work starts or a contract is signed. A certificate summarizes coverage but does not alter the policy.
A contract may require your customer or project owner to be named as an additional insured. This status provides limited protection under your policy for specific liabilities related to your operations. Requirements vary, so review contracts and request the appropriate endorsement.
Tuve Insurance can explain certificate requests, additional insured requirements, waiver of subrogation, and policy limits before your project begins.
How Much Does General Liability Insurance Cost in Minnesota?
The cost of general liability insurance in Minnesota depends on your industry, revenue, payroll, subcontractor expenses, claims history, coverage limits, deductible, and operations. For example, a low-risk office will have different pricing than a roofing contractor, restaurant, manufacturer, or business with high customer traffic.
Insurers may also consider how long you have operated, safety procedures, and claim patterns in your industry. The Minnesota Department of Commerce notes that business operations, financial stability, state law, and risk-management practices can influence liability underwriting.
The lowest general liability insurance quote may not offer the best value. Compare exclusions, classifications, products-completed operations coverage, aggregate limits, defense provisions, endorsements, and carrier service, not just the premium.
Why Choose Tuve Insurance?
Tuve Insurance is a veteran-owned independent agency in Lakeville, Minnesota. We represent multiple insurance companies, allowing us to compare general liability insurance options across several carriers. We consider where work is performed and what contracts require.
We can also coordinate general liability with commercial property, business owners’ policy coverage, commercial auto, workers’ compensation, cyber liability, professional liability, and commercial umbrella insurance.
Request a General Liability Insurance Quote
A single accident or lawsuit can create expenses that threaten your business. Protect your company before a customer, landlord, or project manager requests proof of insurance.
Contact Tuve Insurance for a general liability insurance quote in Lakeville, MN.
Call 952-469-0428 today. We will help you compare business liability insurance coverage, limits, endorsements, and pricing from multiple carriers so you can move forward with confidence.
Frequently Asked Questions
Minnesota does not impose one universal general liability requirement on every business. However, licensing rules, leases, customer contracts, lenders, or project owners may require coverage and specific limits.
Generally, no. Workers’ compensation insurance typically addresses employee work-related injuries. General liability focuses primarily on covered injuries and property damage involving third parties.
Usually not. Claims arising from professional advice, errors, or failure to provide promised services generally require professional liability insurance, also called errors and omissions insurance.
Yes. Many eligible small businesses purchase a business owners policy that combines general liability and commercial property coverage. Commercial auto, workers’ compensation, and professional liability normally require separate protection.